A large IRS tax debt can feel overwhelming—but it doesn’t necessarily mean you have to pay everything immediately or face the IRS alone.
If you owe more than $50,000, getting an IRS installment agreement is usually more complicated than a standard payment plan. The IRS may ask for detailed financial information and will closely review your ability to pay before approving an agreement.
At Arora Law P.C., our tax attorneys help individuals, business owners, executives, self-employed professionals, and investors resolve large IRS tax debts. We gather the needed financial information, talk directly with the IRS, and work out payment plans that fit your situation and IRS rules.
✓ IRS tax debts exceeding $50,000
✓ Existing or defaulted IRS payment plans
✓ IRS collection notices, liens, and levy issues
✓ Revenue Officer cases
✓ Complex financial disclosure requirements
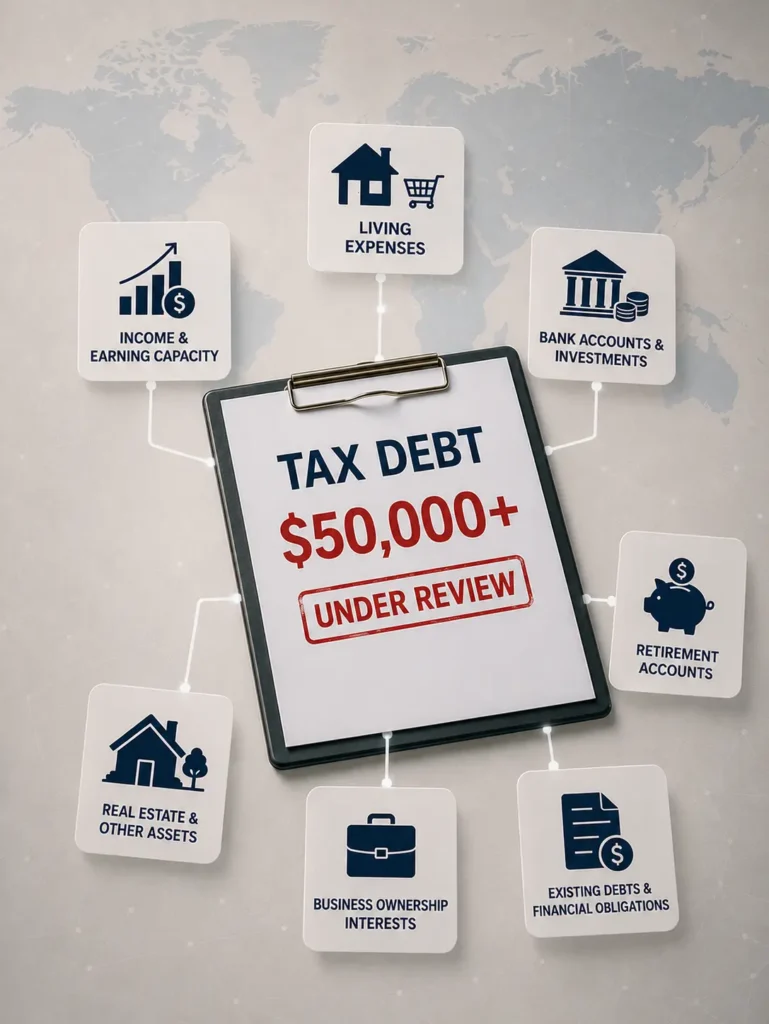
The IRS generally reviews larger tax debts much more closely than smaller balances.
Instead of simply accepting the monthly payment you request, the IRS may evaluate:
The outcome often depends on how your financial information is presented and whether your proposed payment matches your documented ability to pay.
Many taxpayers are surprised to learn that larger installment agreement cases often involve negotiations rather than simply submitting a form.
Depending on your circumstances, the IRS may require:
Providing complete and accurate information from the start helps avoid delays and repeated IRS requests.
Many taxpayers postpone dealing with the IRS because they are unsure what to do next.
Unfortunately, delaying action may allow interest and penalties to continue growing while collection activity progresses.
Depending on your case, the IRS may:
Taking action early may preserve more resolution options and help avoid unnecessary collection actions.
Not every taxpayer with a large IRS balance needs the same solution.
An installment agreement may be appropriate if you:
Before recommending an installment agreement, we evaluate whether another IRS collection option may better fit your situation.
We review your:
This allows us to determine the most appropriate resolution strategy.
After you sign Form 2848 (Power of Attorney), we communicate directly with the IRS on your behalf.
Instead of dealing with IRS Collection personnel yourself, we can:
For taxpayers owing more than $50,000, financial disclosure is often one of the most important parts of the process.
We help prepare:
Our attorneys work directly with the IRS to negotiate payment terms based on your documented financial condition and applicable IRS collection procedures.
If your financial situation changes in the future, we can also evaluate whether your agreement may be modified.
Many clients come to us because they are experiencing one or more of the following:
If any of these situations sound familiar, we can help you understand your options.
When your tax debt is substantial, experience matters.
Our attorneys focus on federal tax controversy and IRS collection matters. We understand the documentation, financial analysis, and negotiations that larger installment agreement cases often require.
From your initial consultation through IRS approval and ongoing compliance, we work to make the process as straightforward as possible while protecting your rights throughout the collection process.
Not necessarily.
Many taxpayers seek professional assistance after receiving IRS collection notices or after their tax debt has grown substantially. Even if you owe more than $50,000, there may still be options available depending on your financial circumstances and IRS requirements.
Possibly.
Many taxpayers with significant tax debts qualify for installment agreements. However, unlike many smaller balances, the IRS often requires detailed financial disclosures before approving a payment plan.
Usually not.
For larger tax debts, the IRS generally reviews your income, expenses, assets, and overall ability to pay before determining whether your proposed payment is acceptable.
Ignoring IRS notices generally does not stop the collection process.
Depending on your circumstances, the IRS may continue collection activity, including filing a federal tax lien, issuing levy notices, or taking other collection actions authorized by law.
You may still have options.
If your financial circumstances have changed, it may be possible to request a modification of your installment agreement or explore another IRS collection alternative.
No.
After you authorize us using Form 2848 (Power of Attorney), we can communicate directly with the IRS on your behalf, respond to requests for information, and negotiate your case.
Generally, no.
An installment agreement usually prevents certain collection actions while it remains in effect, but interest and applicable penalties generally continue to accrue until the tax debt is paid in full.
Every case is different.
Before recommending an installment agreement, we review your tax situation, financial condition, and IRS collection history to determine whether a payment plan—or another IRS resolution option—may be more appropriate.
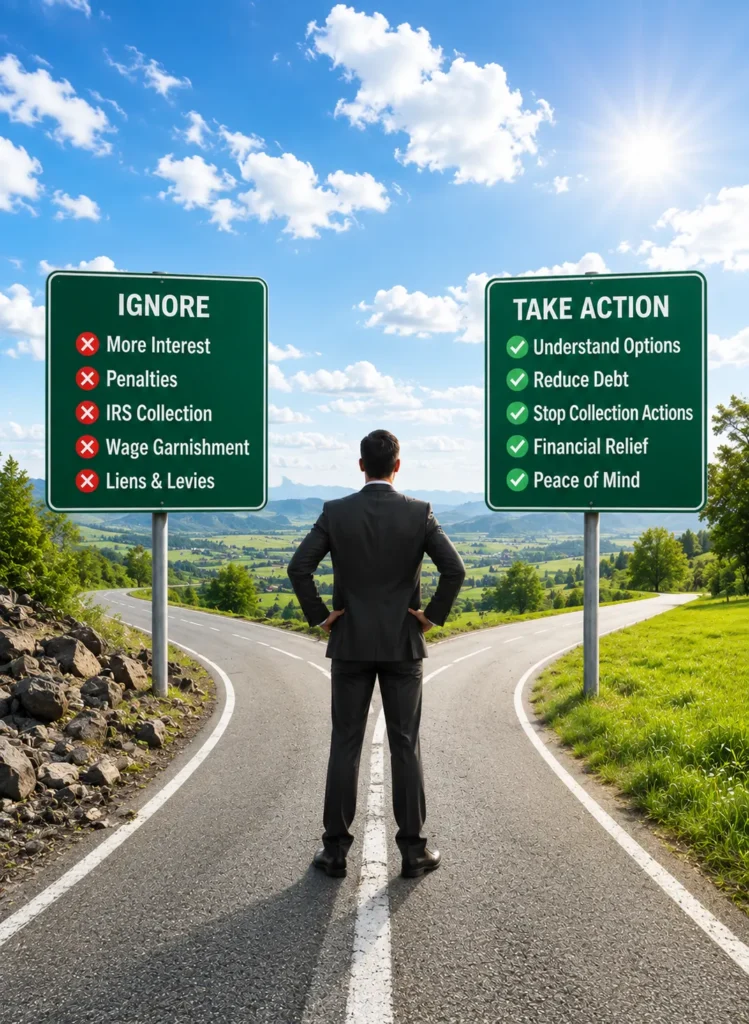
The longer a large IRS tax debt remains unresolved, the more difficult it can become as interest, penalties, and collection activity continue.
Speaking with an experienced tax attorney early can help you understand your options and develop a strategy before the situation becomes more serious.
Whether you owe $50,000, $150,000, or more, we’re here to help you navigate the IRS collection process with confidence.
✓ Attorney representation before the IRS
✓ Guidance for taxpayers with significant tax debts
✓ Confidential consultation
✓ Individuals and businesses welcome
This website uses automated translation tools for convenience. The English version shall prevail in case of any inconsistency. Arora Law P.C. is not responsible for the accuracy of translations.