The International Fuel Tax Agreement (IFTA) is an agreement between 48 U.S. states and 10 Canadian provinces. It makes fuel-tax reporting easier for trucking companies that travel across U.S. state or Canadian provincial borders where IFTA applies. However, U.S. states such as Alaska, Hawaii, and the District of Columbia are not members of IFTA. Also, Mexico is not a member of IFTA.
Before getting into the details of IFTA and its implications for a Mexican trucking company, let’s first discuss how IFTA works.
The International Fuel Tax Agreement (IFTA) simplifies fuel-tax reporting for trucking companies that operate across the 48 contiguous U.S. states and 10 Canadian provinces. Instead of filing separate fuel-tax returns in each participating jurisdiction, a qualifying trucking company can obtain one IFTA license and file a single quarterly fuel-tax return.
Next, let’s look at which vehicles qualify for IFTA.
International Fuel Tax Agreement (IFTA) generally applies to qualified motor vehicles used to transport people or property across participating state or provincial borders.
A vehicle generally qualifies if it operates in two or more IFTA jurisdictions and meets at least one of these requirements:
For example, a three-axle truck traveling from Texas into Oklahoma may qualify even if it weighs less than 26,000 pounds. However, a two-axle truck weighing 20,000 pounds generally would not qualify on its own under these criteria.
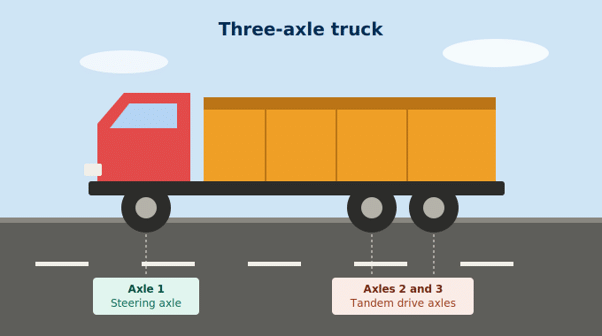
Generally, an axle connects the wheels on opposite sides of a vehicle and supports its weight. A three-axle truck usually has one front axle for steering and two rear axles for driving. The two rear axles are called a tandem axle.
The following is a demonstration image of a three-axle truck
Next, let’s understand the concept of base jurisdiction under IFTA.
A base jurisdiction is the state or province where the trucking company registers for the International Fuel Tax Agreement (IFTA). It is generally the jurisdiction where the company registers its qualifying vehicles, manages its trucking operations, and maintains its operating records.
The company obtains its IFTA license through its base jurisdiction. It then files its quarterly returns with that jurisdiction, even when its trucks travel through several other participating states or provinces.
Next, let’s understand how IFTA calculates fuel tax.
When a trucking company buys fuel, the purchase price generally includes the local state-applicable fuel taxes. However, the truck may use that fuel while traveling through several states.
Under the International Fuel Tax Agreement (IFTA), each participating jurisdiction receives tax on the fuel consumed within its borders. The amount of fuel consumed in each jurisdiction is generally calculated using the miles traveled there and the truck’s average miles per gallon.
Each quarter, the company reports the following to the base jurisdiction:
The base jurisdiction uses this information to calculate the tax due or credit available for each jurisdiction.
If the company has already paid fuel tax on more fuel than it is allocated to that jurisdiction, it may receive a credit. If it has not paid enough tax on the fuel consumed there, it may owe additional tax.
Next, let’s understand how the trucking company files IFTA returns.
The trucking company files one International Fuel Tax Agreement (IFTA) return every three months with its base jurisdiction. The return generally includes:
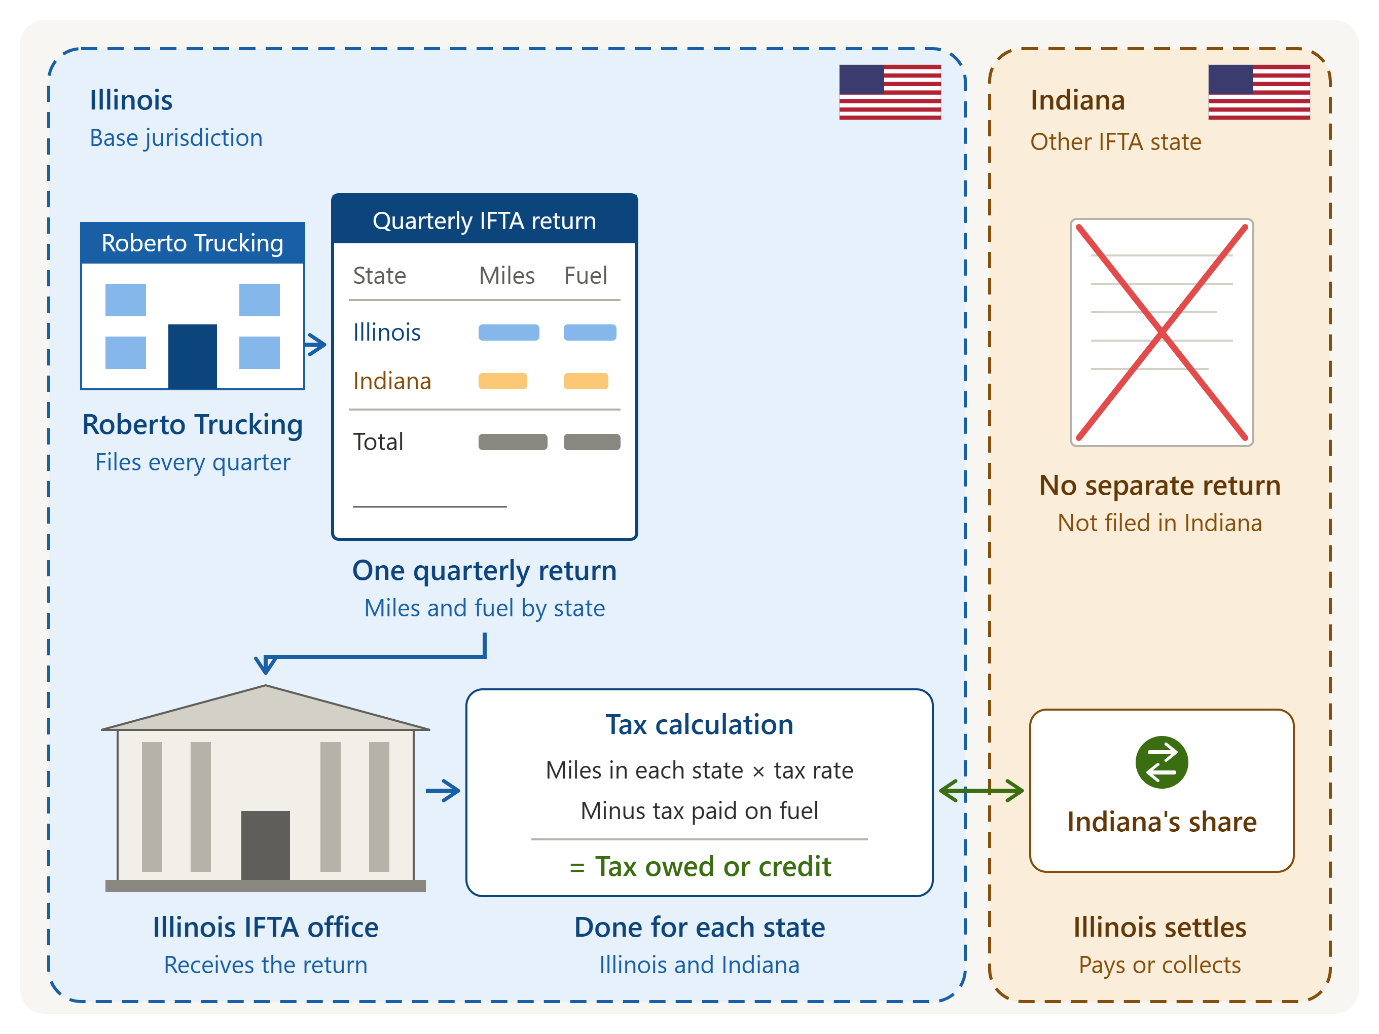
The base jurisdiction calculates the tax owed to each participating jurisdiction and handles the payments or credits through the IFTA system. This allows the company to meet its fuel-tax reporting obligations through one quarterly return rather than filing separately in every state or province.
Let’s understand IFTA and how it works through a simple example.
For example, suppose a trucking company is based in Texas and operates trucks in Texas, Oklahoma, and Louisiana during a quarter. Here, the base jurisdiction is Texas. It purchases fuel in Texas but also uses that fuel while driving through Oklahoma and Louisiana.
The company records the miles its trucks travel in each state and the fuel purchased during the quarter. It uses the fleet’s average miles per gallon to calculate the fuel consumed in each state.
The company then reports this information on its Texas IFTA return, as Texas is the base jurisdiction. Texas calculates the fuel tax due or credit available for each state and handles the corresponding payments through the IFTA system.
As a result, the trucking company can report its fuel-tax activity for all three states through one quarterly return filed in Texas.
However, please note that Mexico is not part of IFTA. But a Mexican trucking company operating its trucks in the U.S. may be able to use IFTA if it meets certain requirements.
Next, let’s understand whether a Mexican trucking company can use IFTA.
A Mexican trucking company generally cannot use Mexico as its International Fuel Tax Agreement (IFTA) base jurisdiction because Mexico is not a member of the agreement.
For example, Humberto Trucking Inc. is based in Tijuana, Mexico. It uses trucks registered in Mexico to transport goods from Mexico to Texas. Because Mexico is not part of IFTA, Humberto Trucking Inc. likely cannot obtain an IFTA license through Mexico.
However, a Mexican-owned company may qualify for an IFTA license through its U.S. operations if those operations meet the base jurisdiction requirements of an IFTA member state. Once the company meets these requirements, the IFTA member state can serve as its IFTA base jurisdiction.
For example, Illinois requires the following conditions to be met before issuing an IFTA license:
The company should satisfy these requirements before Illinois can serve as its IFTA base jurisdiction. Other application and documentation requirements may also apply.
Let’s understand through a simple example, which is as follows:
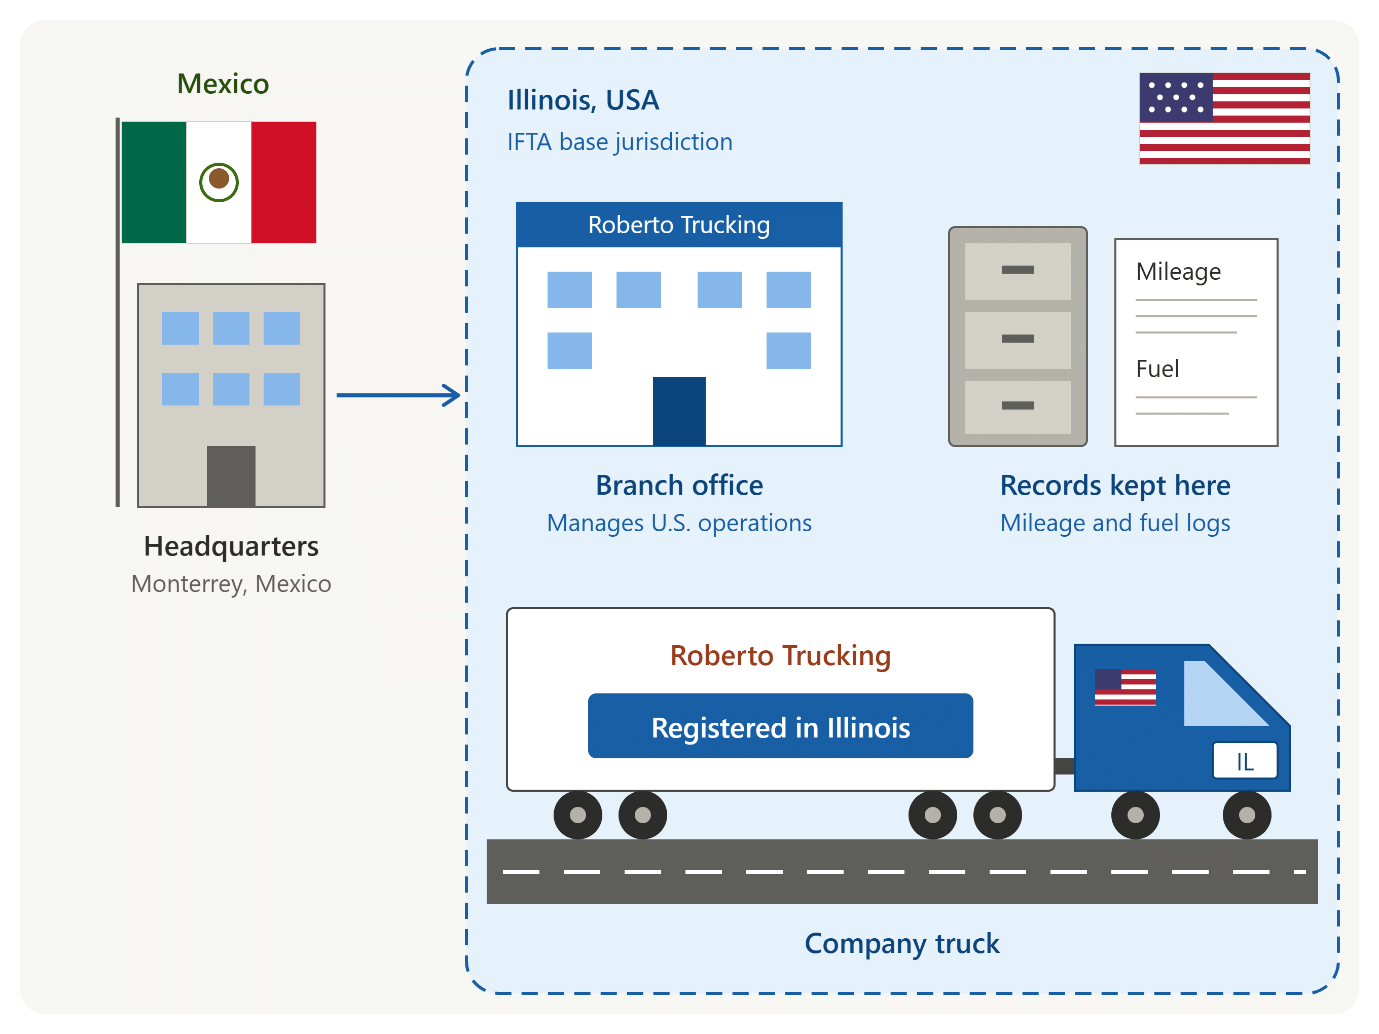
For example, suppose Roberto Trucking, a Mexican company based in Monterrey, Mexico, operates a U.S. trucking business through an Illinois branch.
Roberto Trucking is a Mexican company based in Monterrey, Mexico. It runs its U.S. trucking business through a branch in Illinois. To use Illinois as its IFTA base jurisdiction, the company must likely:
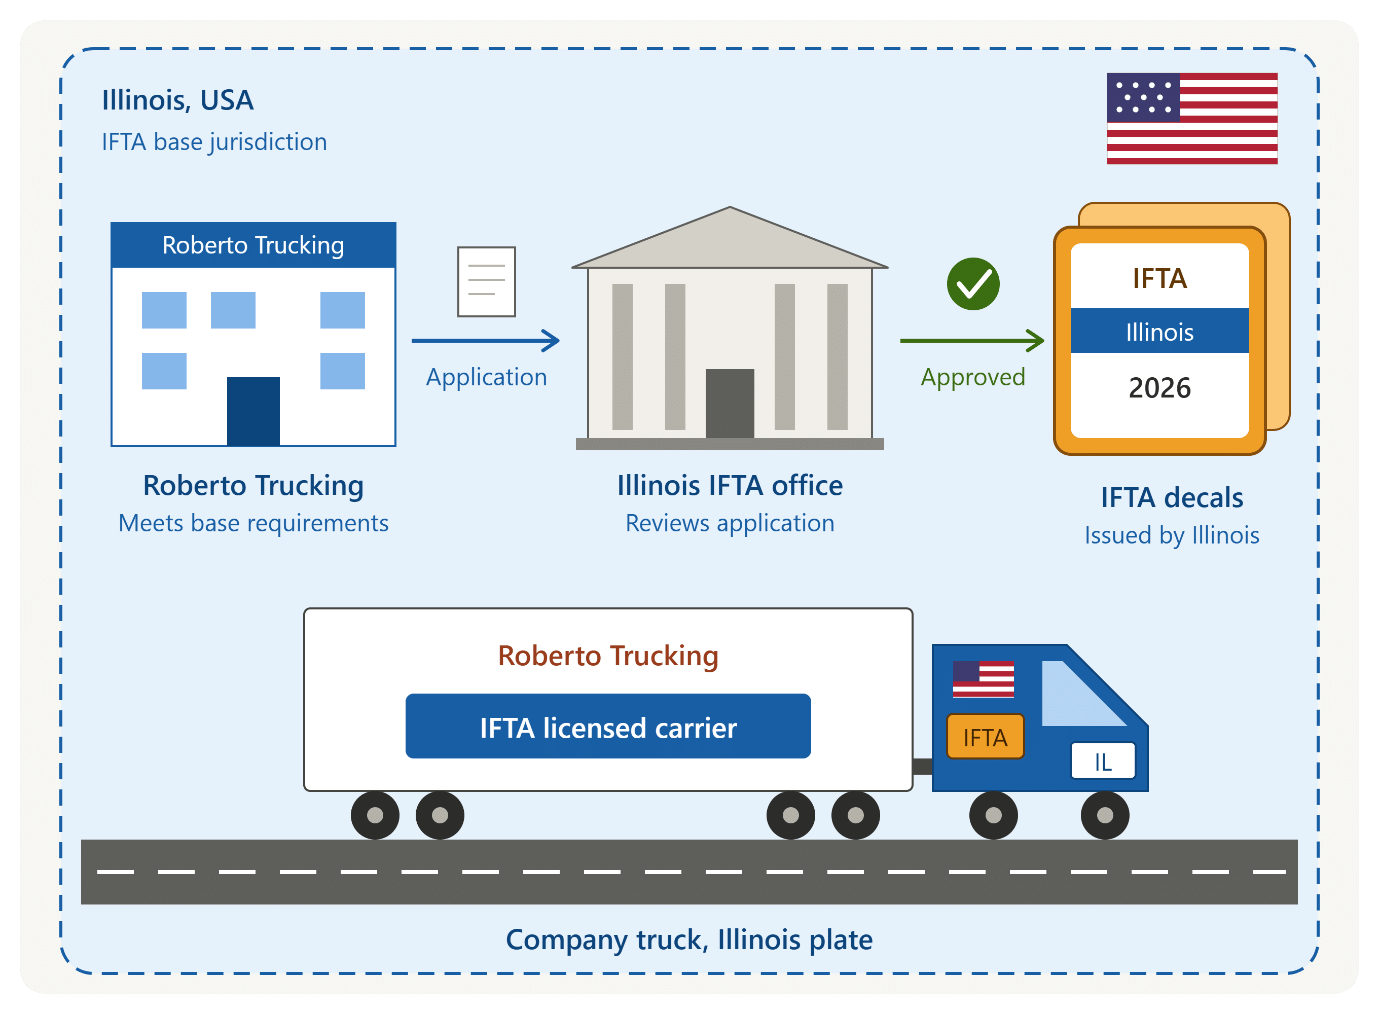
If Roberto Trucking meets all of Illinois’s base jurisdiction requirements and its application is approved, Illinois issues it an IFTA license.
The company’s trucks deliver goods in both Illinois and Indiana. Along the way, they drive miles, buy fuel and paid local applicable tax in each state.
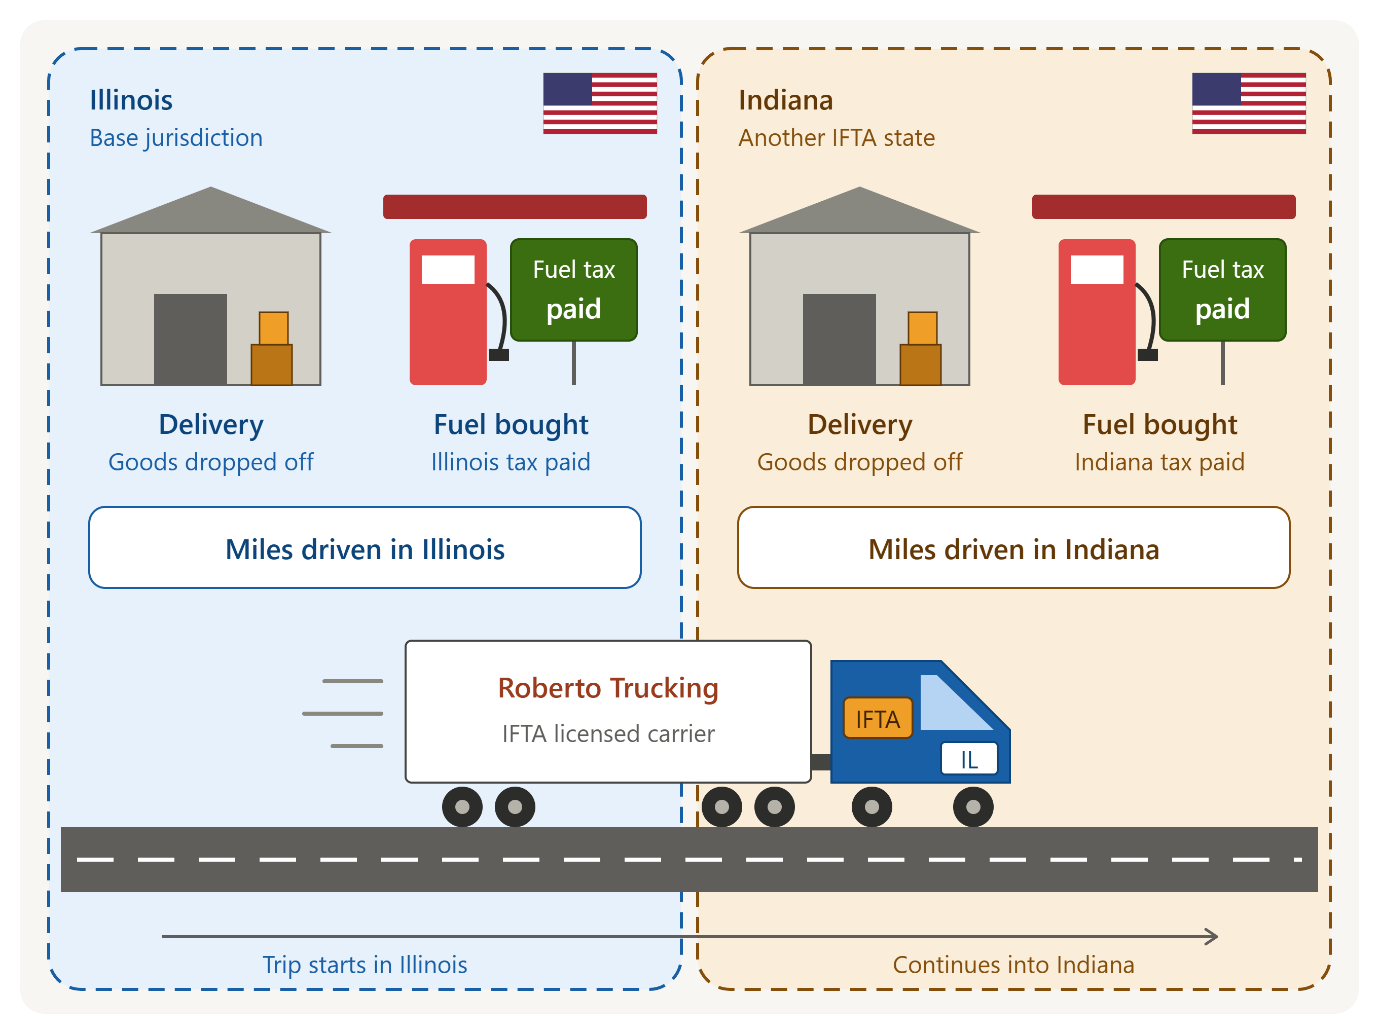
Instead of filing separate fuel-tax returns in Illinois and Indiana, Roberto Trucking files a single quarterly IFTA return with Illinois. The return reports the miles driven and fuel purchased in each state. Fuel tax is calculated based on the miles driven in each state and the applicable fuel-tax rate, with credit given for tax paid on fuel purchased. Illinois calculates the tax owed or credit due for each state and settles the amounts with the other jurisdictions.
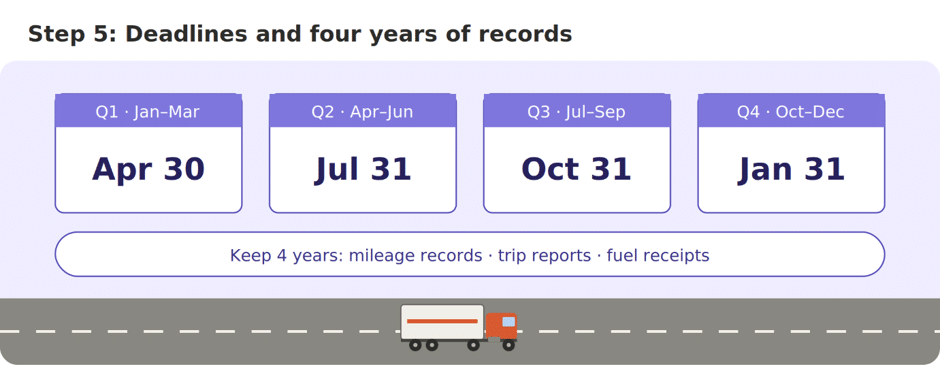
Quarterly returns are due on April 30, July 31, October 31, and January 31. Roberto Trucking must keep its mileage records, trip reports, and fuel receipts for four years.
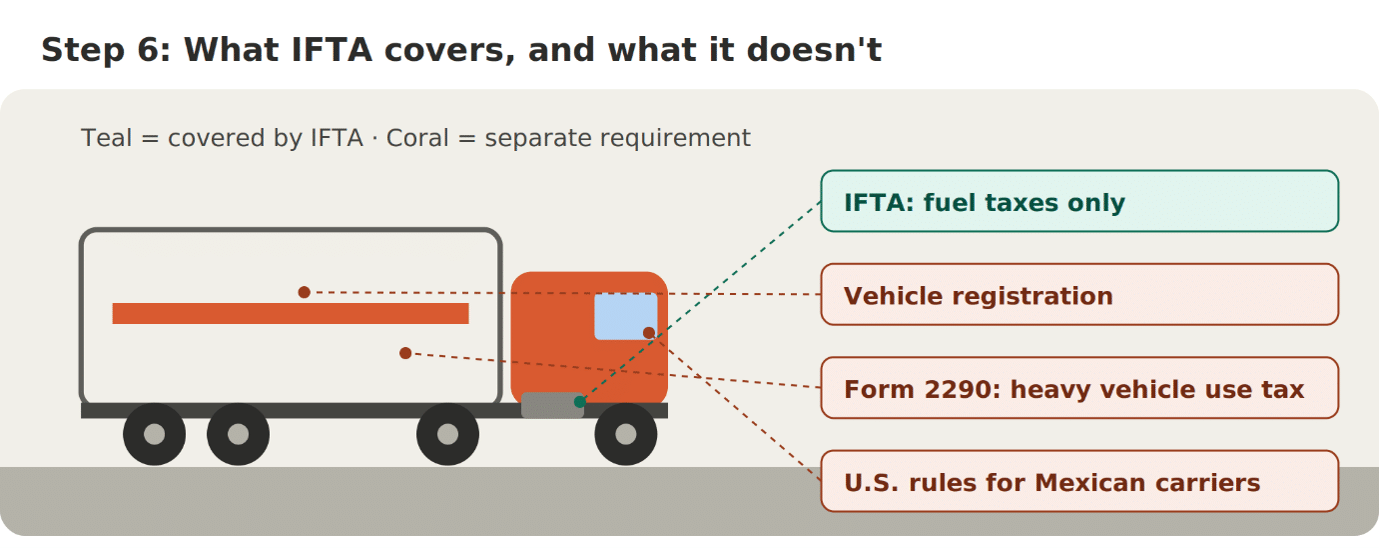
IFTA covers fuel taxes only. Roberto Trucking must separately meet other obligations, including vehicle registration, the federal Heavy Vehicle Use Tax (Form 2290), and applicable U.S. trucking regulations for Mexican companies.
A Mexican trucking company should therefore check whether it qualifies for IFTA and what fuel-tax requirements apply in each U.S. state where it operates.